
The next lending decision is waiting on a document
A borrower submits a renovation budget. Another attachment contains an older total. The contractor’s license has expired, and someone needs to ask for a replacement.
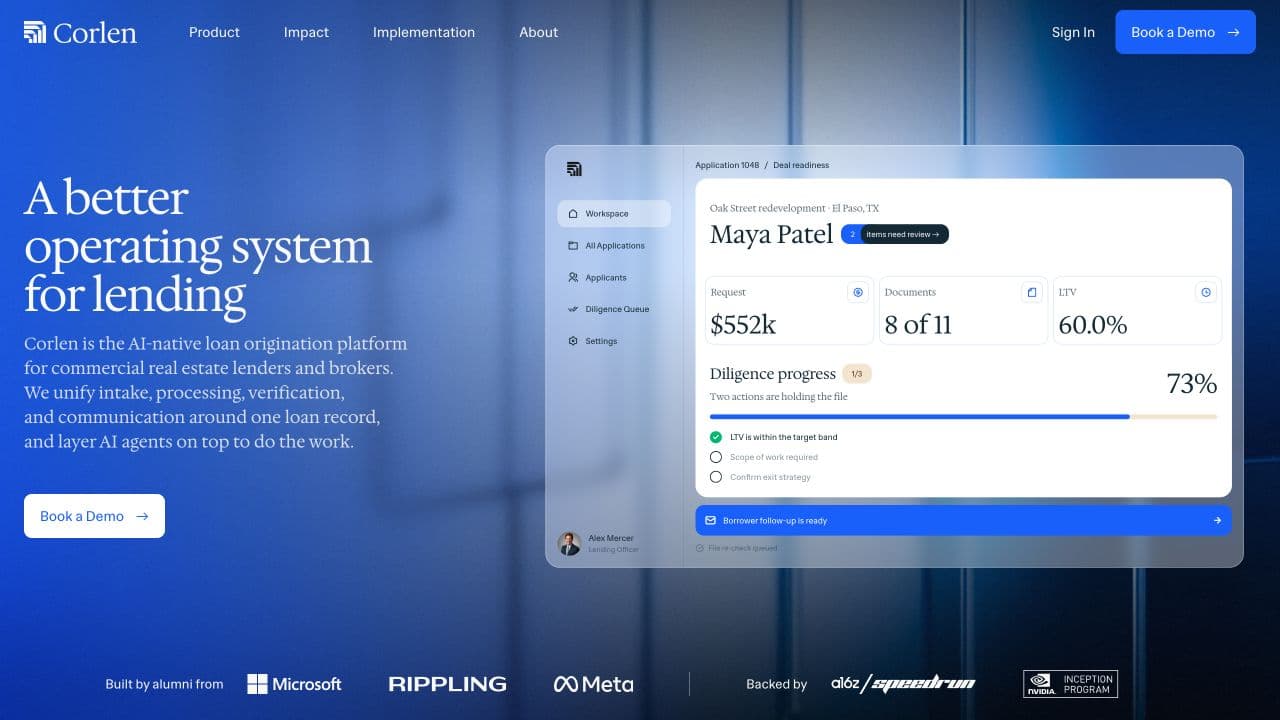
Corlen’s public loan-processing demonstration brings those kinds of exceptions into one record. Agents organize the documents, check requirements, and prepare the follow-up needed to move the file forward. [1]
The platform is built for commercial real estate lenders, brokers, and financial institutions. The lending team keeps the final credit decision. [1][3]
Keep the file and its requirements together
A Corlen loan record combines borrower information, documents, communication, lender requirements, and decisions. Teams can see what has arrived, what remains missing, and which items need attention. [1][3]
Agents read incoming documents and compare them with the configured program and lender guidelines. They can flag missing information, inconsistent figures, and expired material for review. [1]
The record preserves the source and status behind a flag. A reviewer can examine the underlying document and decide what the file needs next. [1]
Move the exception back into the borrower conversation
When a document is missing or stale, Corlen can prepare or send a borrower follow-up under the team’s configured workflow. Incoming replacements are checked against the outstanding requirements. [1]
In the public example, a budget mismatch and an expired contractor license create separate review flags. An updated budget can resolve one requirement while the license remains outstanding. These are demonstration records. [1]
Keeping that work attached to the loan gives the next reviewer the current state of the file. The team can follow the communication and checks through the audit trail. [1]
Bring the lender’s own rules into the workflow
Corlen supports lender and broker workflows, including the different requirements a broker may manage across loan programs. Existing guidelines inform the checks and document requirements. [1]
The implementation connects to the team’s current loan origination and point-of-sale systems. Teams review the configured requirements and approval steps before using the agents in the live process. [1]
The agent handles recurring processing work, while the lender’s reviewers handle exceptions and decisions that require their judgment. [1][3]
A lending operator and a production AI engineer
Waruna Yapa and Meheresh Yeditha founded Corlen in 2026 and joined a16z speedrun’s seventh cohort. Yapa is CEO and Yeditha is CTO. [2][3]
Yapa founded a real estate investment firm and closed 25 deals across mortgage and portfolio-financing structures. His prior technology experience includes Meta, LinkedIn, and Microsoft. [3]
Yeditha built and led production AI and infrastructure at Microsoft and Rippling. Together, the founders are applying that lending and engineering experience to the work between a borrower’s first submission and a complete file. [3]
Where Corlen ranks
A ranked comparison is not yet available for Corlen.
The bigger picture
A loan file changes with every new document and borrower reply. Corlen keeps its requirements and processing work connected, giving the lending team a clearer path to the next decision.
Written by SOTA2 from Corlen’s public materials. Customer experiences and product plans are reported by Corlen. Ranking analysis and comparison data are from SOTA2.